
…As Bond Market Recovery Remains Uncertain
News Desk REPORT
Ghana faces a major domestic debt refinancing challenge over the next two years, with GH¢111 billion in restructured domestic bonds falling due in 2027 and 2028.
The obligations, comprising GH¢58 billion due in 2027 and GH¢53 billion in 2028, are largely instruments accepted by banks, pension funds and other investors under the 2022/23 Domestic Debt Exchange Programme (DDEP).
The scale and timing of the maturities have raised concerns about Ghana’s ability to refinance the obligations without renewed pressure on the domestic financial market.
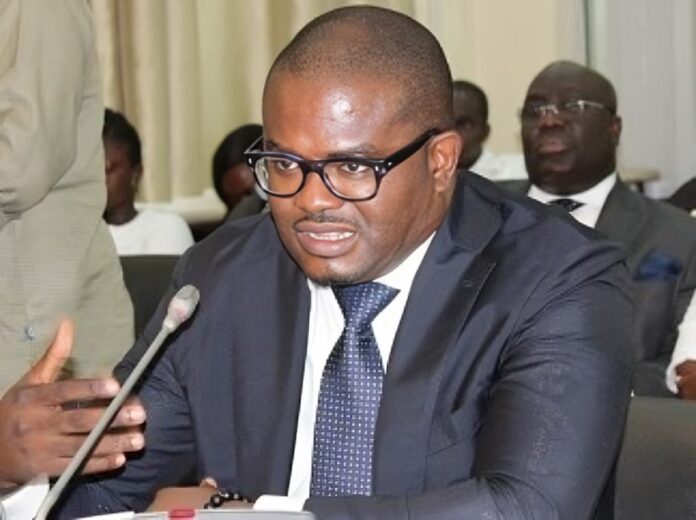
An analysis by former Minister of State at the Ministry of Finance, Charles Adu Boahen, describes the situation as a “maturity wall”, noting that the principal on the affected instruments is payable in bullet payments rather than being spread over several years.
This means the government will have to mobilise large amounts of financing around four settlement dates instead of gradually amortising the debt.
A sharp concentration of maturities
The maturity profile creates a significant concentration of domestic debt obligations in 2027 and 2028.
According to the analysis, annual domestic debt maturities after 2028 range between GH¢4.9 billion and GH¢9.3 billion.
By comparison, more than GH¢50 billion is scheduled to mature in each of 2027 and 2028.
The combined GH¢111 billion due in those two years is therefore substantially larger than the GH¢69 billion spread across the following ten years.
The analysis argues that the central challenge is therefore less about the overall size of Ghana’s domestic debt than the concentration of repayment obligations within a relatively short period.
Refinancing rather than repayment
Mr Adu Boahen argues that an obligation of this magnitude would ordinarily not be settled entirely from tax revenues.
Instead, the government would be expected to refinance the maturing securities by issuing new debt, making the condition of Ghana’s domestic bond market critical to managing the maturities.
Government has already begun building a Sinking Fund intended to provide liquidity for upcoming debt obligations.
The fund reportedly held GH¢15.6 billion as of July 22, 2026, while government has indicated that it is targeting GH¢30 billion by the end of the year.
According to the analysis, that amount could cover the February 2027 bullet payment, but further refinancing of roughly GH¢25 billion to GH¢30 billion would still be required in each of 2027 and 2028.
This creates a requirement for the government to restore sufficient investor confidence and market capacity before the largest maturities arrive.
Bond market remains the critical issue
One of the major concerns identified in the analysis is the state of Ghana’s domestic bond market following the debt exchange.
Although overall trading activity on the Ghana Fixed Income Market has recovered to levels comparable with the pre-DDEP period, the composition of that trading has changed significantly.
Treasury bills and sell-and-buy-back transactions now account for the bulk of market activity, while outright trading in government bonds has fallen sharply.
The analysis puts outright trading in government notes and bonds at less than 10 per cent of secondary-market volume, compared with about 90 per cent before the DDEP.
This means that while there may be substantial activity in the broader fixed-income market, the government has yet to fully restore a liquid market for longer-dated bonds.
The April 2026 seven-year government issue offered an indication of the challenge. It raised GH¢2.7 billion against GH¢3.1 billion in bids.
While the issue was successfully cleared, the analysis argues that the level of demand would not, by itself, demonstrate the capacity to absorb the much larger annual refinancing requirement expected in 2027 and 2028.
DDEP postponed rather than eliminated the obligation
The analysis also questions the extent to which the 2022/23 Domestic Debt Exchange reduced Ghana’s underlying repayment burden.
Citing an analysis by Black Star Analytics, it says total coupon-and-principal payments increased from GH¢223.8 billion before the exchange to GH¢266.5 billion afterwards.
Nominal principal reportedly increased from GH¢121.2 billion to GH¢167.7 billion, although the weighted average coupon fell from 18.03 per cent to 15.1 per cent.
The weighted average maturity, according to the analysis, remained at six years.
The implication presented by the former Finance Ministry official is that the debt exchange altered the timing and cost structure of the obligations but did not remove the need for substantial future refinancing.
Sinking Fund faces limitations
The analysis also cautions against viewing the Sinking Fund as equivalent to accumulated budgetary savings.
It notes that the 2026 Budget projects an overall deficit of GH¢64.2 billion, equivalent to four per cent of GDP, alongside a primary deficit of GH¢6.5 billion.
Against that fiscal position, money accumulated in the Sinking Fund must ultimately come from some combination of borrowing, reduced expenditure or asset sales.
Mr Adu Boahen therefore describes the fund as an important cash-management and signalling mechanism but argues that it should not be treated as a complete solution to the maturity wall.
The analysis recommends deploying part of the fund strategically through market-based transactions, including potential buybacks of outstanding debt.
Current economic conditions provide some breathing room
The assessment acknowledges that Ghana enters the refinancing period from a considerably different macroeconomic position than it faced during the debt crisis.
According to the analysis, Ghana successfully exited the IMF programme in July 2026, while inflation had fallen from above 50 per cent at its peak to around five per cent.
The policy rate has also declined substantially since January 2025, while borrowing costs have fallen sharply compared with levels recorded during the debt crisis.
Five-year borrowing costs are cited as having fallen below 10 per cent, compared with more than 30 per cent three years earlier.
These developments could provide a more favourable environment for rebuilding the domestic bond market.
However, the analysis stresses that improved macroeconomic conditions do not eliminate the underlying refinancing requirement.
It also points to the 2028 election year as an additional fiscal consideration because GH¢53 billion is scheduled to mature during that year.
Investor demand remains a concern
Another challenge is the willingness of investors to absorb new long-term government securities.
The analysis cites an institutional investor survey by Black Star Group in which 77 per cent of respondents reportedly said they would require at least a 200-basis-point premium over the 364-day Treasury bill rate to participate in new issuance.
It also notes that many investors remain uncertain about Ghana’s medium-term debt strategy.
This creates a potential mismatch between the government’s need to raise GH¢25 billion to GH¢30 billion annually to refinance the maturing securities and the current capacity of the market to absorb long-term government bonds.
Why the bond market matters beyond the maturity wall
The analysis argues that restoring a functioning domestic bond market is important not only because of the 2027/28 maturities but also because of its wider implications for Ghana’s financial system.
A functioning government bond market provides a reference yield curve against which banks, insurers and companies price other forms of credit.
Long-term government securities also allow pension funds and insurance companies to match long-term assets with their long-term liabilities.
The analysis further argues that a liquid bond market could reduce reliance on short-term Treasury bills and lower rollover risk.
At present, heavy dependence on short-term instruments means government must repeatedly return to the market to refinance maturing obligations.
Longer-dated bonds would allow the government to lock in financing for extended periods and better match debt with long-lived public investments.
A stronger domestic bond market could also reduce reliance on foreign-currency borrowing because cedi-denominated debt does not automatically increase in cedi terms when the local currency depreciates.
Proposed measures
Mr Adu Boahen’s analysis proposes several measures to reduce the refinancing pressure before the major maturities arrive.
Among them is the early launch of voluntary switch auctions that would allow holders of 2027 and 2028 securities to exchange them for longer-dated instruments before the government reaches the maturity dates.
It also recommends using the Sinking Fund for open-market buybacks, placing the fund on a statutory footing and publishing its balance and funding sources regularly.
Other proposals include establishing a rolling three-year government issuance calendar, creating benchmark bonds at key maturities, and improving secondary-market liquidity.
The analysis also calls for measures to revive the interbank repo market, strengthen market-making obligations for primary dealers and broaden the investor base through retail, diaspora and other targeted bond products.
The window for action
The analysis concludes that Ghana has a limited period in which to address the maturity concentration before the obligations become immediate.
Its central argument is that the government should reduce the size of the 2027–28 maturity wall through voluntary exchanges and buybacks while simultaneously rebuilding the infrastructure and investor confidence needed for a functioning bond market.
If those measures succeed, the GH¢25 billion to GH¢30 billion annual refinancing requirement could become a more routine funding exercise.
If the bond market remains illiquid and investor participation stays weak, however, the refinancing of the 2027 and 2028 maturities could become substantially more difficult.
The analysis therefore frames the immediate challenge not simply as finding money to repay GH¢111 billion, but as ensuring that Ghana has a sufficiently deep and functioning domestic capital market to refinance the obligations when they fall due.
The views and recommendations are those of Charles Adu Boahen and are based on sources including the Bank of Ghana, Ministry of Finance fiscal documents, Ghana Fixed Income Market reports, IMF documentation, Fitch Ratings, Central Securities Depository data and analyses by Black Star Analytics.
thebusinessmail